 Canada
 United States
 Bahamas
HR Payroll Trinidad and Tobago 2026: Minimum Wage, NIS, PAYE
HR and payroll in Trinidad and Tobago requires NIS contributions at 16.2% total (rising to 19.2% in 2027), based on NIBTT weekly earnings bands, Pay As You Earn (PAYE) income tax at 25% / 30%, and a Health Surcharge of $8.25 weekly. On overtime, first 4 hours beyond 40 a week at 1.5 times, for workers paid up to 1.5 times the minimum wage; the Schedule to the Public Holidays and Festivals Act lists 14 public holidays to track each year. These rules are specific to Trinidad and Tobago. Assumptions from other jurisdictions will cost you money.
- NIS: 16.2% total (employer ~10.8%, employee ~5.4%) in 2026, rising to 19.2% in 2027, on weekly earnings bands. PAYE: TT$90,000 personal allowance; 25% on chargeable income up to TT$1,000,000, 30% on chargeable income above TT$1,000,000.
- Health Surcharge: $8.25 weekly. Overtime: first 4 hours beyond 40 a week at 1.5 times, for workers paid up to 1.5 times the minimum wage.
- Leave: vacation, 2 weeks vacation after 12 months and 220 days worked, this sector only; sick leave, 14 working days sick leave a year after 6 months, topped up over NI sickness benefit, this sector only; maternity leave, 14 weeks of maternity leave, starting 6 weeks before the due date or later
- The Schedule to the Public Holidays and Festivals Act lists 14 public holidays in Trinidad and Tobago, including Eid-ul-Fitr and Divali, whose dates are appointed by the President by Notification.
Most foreign-managed operations in Trinidad and Tobago don't get payroll wrong because they're careless. They assume it works like everywhere else: a company opens a branch, hands payroll to whoever ran it back home, and builds the spreadsheet the way they always have. Then the National Insurance Board of Trinidad and Tobago (NIBTT) flags the contributions, usually inside the first year. The company had been applying a flat 16.2% split evenly between employer and employee, wrong on two counts. The employer-employee split is roughly two-thirds/one-third, not 50/50, and the National Insurance System (NIS) in Trinidad doesn't use a flat percentage at all. It uses weekly earnings bands tied to insurable earnings classes, and every single pay period had been calculated incorrectly. The back-assessment, penalties, and professional fees to unwind it cost more than a year of properly configured payroll software would have. For a software-focused look at platform requirements, see our Trinidad and Tobago HR software guide.
Payroll Deductions: NIS, PAYE, and Health Surcharge
Trinidad and Tobago payroll involves three deductions: NIS, PAYE and the Health Surcharge. Get any of them wrong and the Board of Inland Revenue or NIBTT will find it. These are not honor-system obligations.
NIS Contributions (NIBTT)
The National Insurance Board of Trinidad and Tobago (NIBTT) administers the National Insurance System. As of January 2026, the combined contribution rate is 16.2% of insurable earnings. This is scheduled to rise to 19.2% in 2027 as part of the NIS reform roadmap.
The employer-employee split is not equal. The employer pays two-thirds (approximately 10.8%) and the employee pays one-third (approximately 5.4%). This two-thirds/one-third split is a detail that companies transferring payroll knowledge from other Caribbean markets routinely miss.
Here's why that trips up every spreadsheet-based payroll operation:
- NIBTT does not apply a flat percentage to gross earnings. Instead, it uses a schedule of weekly earnings bands (insurable earnings classes). Each band maps to a fixed weekly contribution amount for the employer and the employee.
- You cannot simply multiply an employee's gross pay by 10.8% to get the employer NIS amount. You need to look up the correct earnings class, find the corresponding contribution amount, and apply that every payroll cycle, for every employee. The NIBTT publishes the contribution tables, and your payroll system needs to reference them precisely.
PAYE Income Tax
Pay As You Earn (PAYE) is the income tax withholding system administered by the Ministry of Finance through the Board of Inland Revenue. The rates are straightforward, but the bands and the allowance must be applied precisely.
The current PAYE bands: TT$90,000 personal allowance; 25% on chargeable income up to TT$1,000,000, 30% on chargeable income above TT$1,000,000.
Every individual gets a personal allowance of TT$90,000 per year. Income below that threshold is not taxed. Source: Inland Revenue Division, PAYE.
Health Surcharge
In addition to NIS and PAYE, employers must deduct a weekly Health Surcharge from employees. The rate is $8.25 weekly. Source: Inland Revenue Division, Health Surcharge.
Each deduction runs on its own basis. NIS comes from the correct earnings band, not a flat percentage, PAYE applies its two rate bands to chargeable income after the personal allowance, and the Health Surcharge is a flat weekly amount.
Minimum Wage and Overtime
The national minimum wage is an hourly rate set under the Minimum Wages Order. The current rate is published by the Ministry: Ministry of Labour (minimum wage).
The Order also decides who its hours and overtime terms cover. Who the overtime terms cover: hours and overtime terms cover workers at up to 1.5 times the minimum wage. Under the Minimum Wages Order, the terms and conditions of work, including the overtime rates, apply only to workers receiving an hourly rate of 1.5 times the national minimum wage or less.
Overtime Rules
For the workers the Order covers:
- Normal working week: normal working week of no more than 40 hours, for workers paid up to 1.5 times the minimum wage. Under the Minimum Wages Order, whose terms and conditions apply only to workers receiving an hourly rate of 1.5 times the national minimum wage or less, the normal working week shall not exceed 40 hours, exclusive of meals and rest breaks.
- Beyond the normal week: first 4 hours beyond 40 a week at 1.5 times, for workers paid up to 1.5 times the minimum wage. Under the Minimum Wages Order, for a worker receiving an hourly rate of 1.5 times the national minimum wage or less, the first 4 hours worked beyond the 40-hour work week are paid at 1.5 times the hourly rate.
- Sundays and public holidays: Sunday (not a normal day) and public holiday: first 8 hours at 2 times, for workers paid up to 1.5 times the minimum wage. Under the Minimum Wages Order, for a worker receiving an hourly rate of 1.5 times the national minimum wage or less, the first 8 hours worked on a Sunday where Sunday is not a normal day, or on a public holiday, are paid at 2 times the hourly rate.
Source: Minimum Wages Order, 2014 (LN 402/2014), clause 7, in Minimum Wages Act, Chap. 88:04.
Any business operating continuous shifts will see holiday premium costs across the 14 public holidays in the Schedule.
Leave Entitlements: Vacation, Sick Leave, and Maternity
Leave in Trinidad and Tobago has a qualifying detail that catches employers who import leave policies from other jurisdictions: vacation in the sector orders depends on days worked, not tenure alone.
Annual Leave (Vacation)
The catering, shop assistants and household assistants orders carry the same vacation term. Each covers its own sector only, so check which order applies to the employee first.
- Catering industry workers: 2 weeks vacation after 12 months and 220 days worked, this sector only. Under the Order, a worker covered by the Minimum Wages (Catering Industry) Order is entitled to 2 weeks of vacation leave with pay annually on completion of 12 months of service from the date of employment, subject to having worked a minimum of 220 days in that period. Source: Minimum Wages (Catering Industry) Order, 1991 (LN 158/1991), clause 6(1), in Minimum Wages Act, Chap. 88:04.
- Shop assistants: 2 weeks vacation after 12 months and 220 days worked, this sector only. Under the Order, a shop assistant covered by the Minimum Wages (Shop Assistants) Order is entitled to 2 weeks of vacation leave with pay annually on completion of 12 months of service from the date of employment, subject to having worked a minimum of 220 days in that period. Source: Minimum Wages (Shop Assistants) Order, 1991 (LN 159/1991), clause 6(1), in Minimum Wages Act, Chap. 88:04.
- Household assistants: 2 weeks vacation after 12 months and 220 days worked, this sector only. Under the Order, a full-time household assistant covered by the Minimum Wages (Household Assistants) Order is entitled to 2 weeks of vacation leave with pay annually on completion of 12 months of service from the date of employment, subject to having worked a minimum of 220 days in that period. Source: Minimum Wages (Household Assistants) Order, 1991 (LN 160/1991), clause 7(1), in Minimum Wages Act, Chap. 88:04.
Workers on extended leave, reduced schedules, or intermittent contracts may reach the anniversary and still fall short of the day count.
Your HR system needs to track actual days worked, not only employment tenure. A worker who started on January 1 but took three months of unpaid leave may not reach the day count by the first anniversary.
Sick Leave
Each of these orders also carries a term for paid illness absence, again for its own sector only:
- Catering industry workers: 14 working days sick leave a year after 6 months, topped up over NI sickness benefit, this sector only. Under the Minimum Wages (Catering Industry) Order, a worker covered by that Order is entitled to 14 working days of sick leave per year with pay, subject to being continuously employed for at least 6 months and producing a medical certificate for any period of illness in excess of 2 days, and payment for sick leave is the difference between the worker's pay and National Insurance sickness benefit. Source: Minimum Wages (Catering Industry) Order, 1991 (LN 158/1991), clause 7(1), in Minimum Wages Act, Chap. 88:04.
- Shop assistants: 14 working days sick leave a year after 6 months, topped up over NI sickness benefit, this sector only. Under the Minimum Wages (Shop Assistants) Order, a shop assistant covered by that Order is entitled to 14 working days of sick leave annually with pay, subject to being continuously employed for at least 6 months and producing a medical certificate for any period of illness in excess of 2 days, and payment for sick leave is the difference between the shop assistant's pay and National Insurance sickness benefit. Source: Minimum Wages (Shop Assistants) Order, 1991 (LN 159/1991), clause 7(1), in Minimum Wages Act, Chap. 88:04.
- Household assistants: 14 working days sick leave a year after 6 months, topped up over NI sickness benefit, this sector only. Under the Minimum Wages (Household Assistants) Order, a household assistant (full-time or part-time) covered by that Order is entitled to 14 working days of sick leave per year with pay, subject to being continuously employed for at least 6 months and producing a medical certificate for any period of illness in excess of 2 days, and the pay is the difference between the assistant's pay and National Insurance sickness benefit. Source: Minimum Wages (Household Assistants) Order, 1991 (LN 160/1991), clause 8(1), in Minimum Wages Act, Chap. 88:04.
Maternity Leave
The Maternity Protection Act is the source for maternity leave.
Maternity leave: 14 weeks of maternity leave, starting 6 weeks before the due date or later. Under the Maternity Protection Act, an employee is entitled to 14 weeks of maternity leave and may proceed on that leave 6 weeks before the probable date of confinement stated in the medical certificate, or at a later date at her discretion, and must return to work no later than 14 weeks from the date she proceeded on leave, subject to section 10.
Who qualifies: 12 months of continuous employment needed. A condition of the maternity leave entitlement under the Maternity Protection Act is that, as of the expected date of confinement which a qualified person certifies, the employee has been continuously employed by that employer for a period of not less than 12 months.
Maternity pay: 1 month full pay and 2 months half pay. During maternity leave under the Maternity Protection Act, an employee is entitled to receive pay from her employer to an amount equivalent to 1 month's leave with full pay and 2 months' leave with half pay. Source: Maternity Protection Act, Chap. 45:57, s 9(1).
The 14 Public Holidays: Cultural Diversity on the Calendar
Public holidays: 14 public holidays in the Schedule. The Schedule to the Public Holidays and Festivals Act lists 14 public holidays in Trinidad and Tobago, including Eid-ul-Fitr and Divali, whose dates are appointed by the President by Notification. Source: Public Holidays and Festivals Act, Chap. 19:05, Schedule (ss 3 and 4). The list reflects the country's Hindu, Muslim, Christian, African, and Indian heritage:
| Holiday |
|---|
| New Year's Day |
| Spiritual Baptist/Shouter Liberation Day |
| Good Friday |
| Easter Monday |
| Indian Arrival Day |
| Corpus Christi |
| Labour Day |
| African Emancipation Day |
| Independence Day |
| Republic Day |
| Divali |
| Eid-ul-Fitr |
| Christmas Day |
| Boxing Day |
Divali and Eid-ul-Fitr move each year. A payroll system that hardcodes holiday dates will miscalculate holiday premiums in any year where the variable holidays shift. For businesses running 24/7 operations in energy, manufacturing, or hospitality, incorrect holiday tracking across the scheduled dates creates compounding payroll errors.
Termination, Retrenchment, and Severance
The Retrenchment and Severance Benefits Act governs what employers owe when positions are eliminated. This is separate from termination for cause or poor performance, and the distinction matters legally.
Retrenchment (Redundancy)
When an employer makes workers redundant, the Act sets both severance and notice.
Severance: 2 weeks' pay per completed year for service of more than 1 and under 5 years; with 5 or more years, 3 weeks' pay in addition for the fifth and each later year. Under the Retrenchment and Severance Benefits Act, a retrenched worker not covered by a registered collective agreement with no less favourable severance terms is entitled, for each completed year of service, to a minimum of 2 weeks' pay at the basic rate (one half month's pay if monthly rated) where service is more than 1 but less than 5 years, and a worker with 5 years or more is in addition entitled, for the fifth and each succeeding completed year, to 3 weeks' pay (three quarters of a month's pay if monthly rated).
Eligibility: more than 1 completed year of service needed. The Retrenchment and Severance Benefits Act does not apply to workers who have not had more than 1 completed year of service, subject to the exception for certain seasonal workers in paragraph (d).
Retrenchment notice: written notice to workers, union and Minister when 5 or more are made redundant. Under the Retrenchment and Severance Benefits Act, an employer who proposes to terminate the services of 5 or more workers for the reason of redundancy must give formal notice of termination in writing to each involved worker, to the recognized majority union and to the Minister.
Notice period: minimum 45 days of formal notice under section 4. Subject to section 7 of the Retrenchment and Severance Benefits Act, the minimum period of the formal notice required by section 4 is 45 days before the proposed date of retrenchment. Source: Retrenchment and Severance Benefits Act, Chap. 88:13, s 18(2) and (3).
Termination for Cause
Termination for misconduct or poor performance calls for documented grounds and a fair process.
Dismissal disputes: a dismissal dispute is a trade dispute. Under the Industrial Relations Act, a trade dispute includes a dispute between an employer and workers of that employer, or a trade union on behalf of those workers, connected with the dismissal of those workers.
Remedy: Industrial Court can order reinstatement or compensation for a dismissal that is harsh and oppressive or contrary to good industrial relations practice. Under the Industrial Relations Act, in any dispute concerning the dismissal of a worker, the Industrial Court may order re-employment or reinstatement, subject to such conditions as it thinks fit to impose, or the payment of compensation or damages, where in its opinion the worker was dismissed in circumstances that are harsh and oppressive or not in accordance with the principles of good industrial relations practice. Source: Industrial Relations Act, Chap. 88:01, s 2(1), definition of "trade dispute".
Operating Across the Caribbean
Many employers in Trinidad and Tobago also operate in the Bahamas, Jamaica, or Antigua and Barbuda. Each jurisdiction has its own contribution structure, tax system, and employment legislation. The NIS system in Trinidad (earnings bands, two-thirds/one-third employer-employee split) is structured differently from NIB in the Bahamas or NIS in Jamaica.
The leave entitlements differ. The overtime triggers differ. The holiday lists differ. The tax structures share almost nothing in common. Running payroll for multiple Caribbean jurisdictions on spreadsheets or disconnected local systems is how compliance errors multiply across borders.
What one client saw
Cable Bahamas, a 850-person telecom operation in the Bahamas, cut payroll processing from 5 days to 1.5 days, a 70% reduction in cycle time, after consolidating to a single platform. That is a Bahamas result. The mechanism behind it, one employee record across all jurisdictions with no cross-system reconciliation, is the same architecture that removes the reconciliation problem from T&T operations.
For employers managing teams in the Bahamas, Jamaica, or Antigua and Barbuda, a single platform that encodes each jurisdiction's rules natively eliminates the manual translation between tax codes and contribution tables that generates the most costly errors.
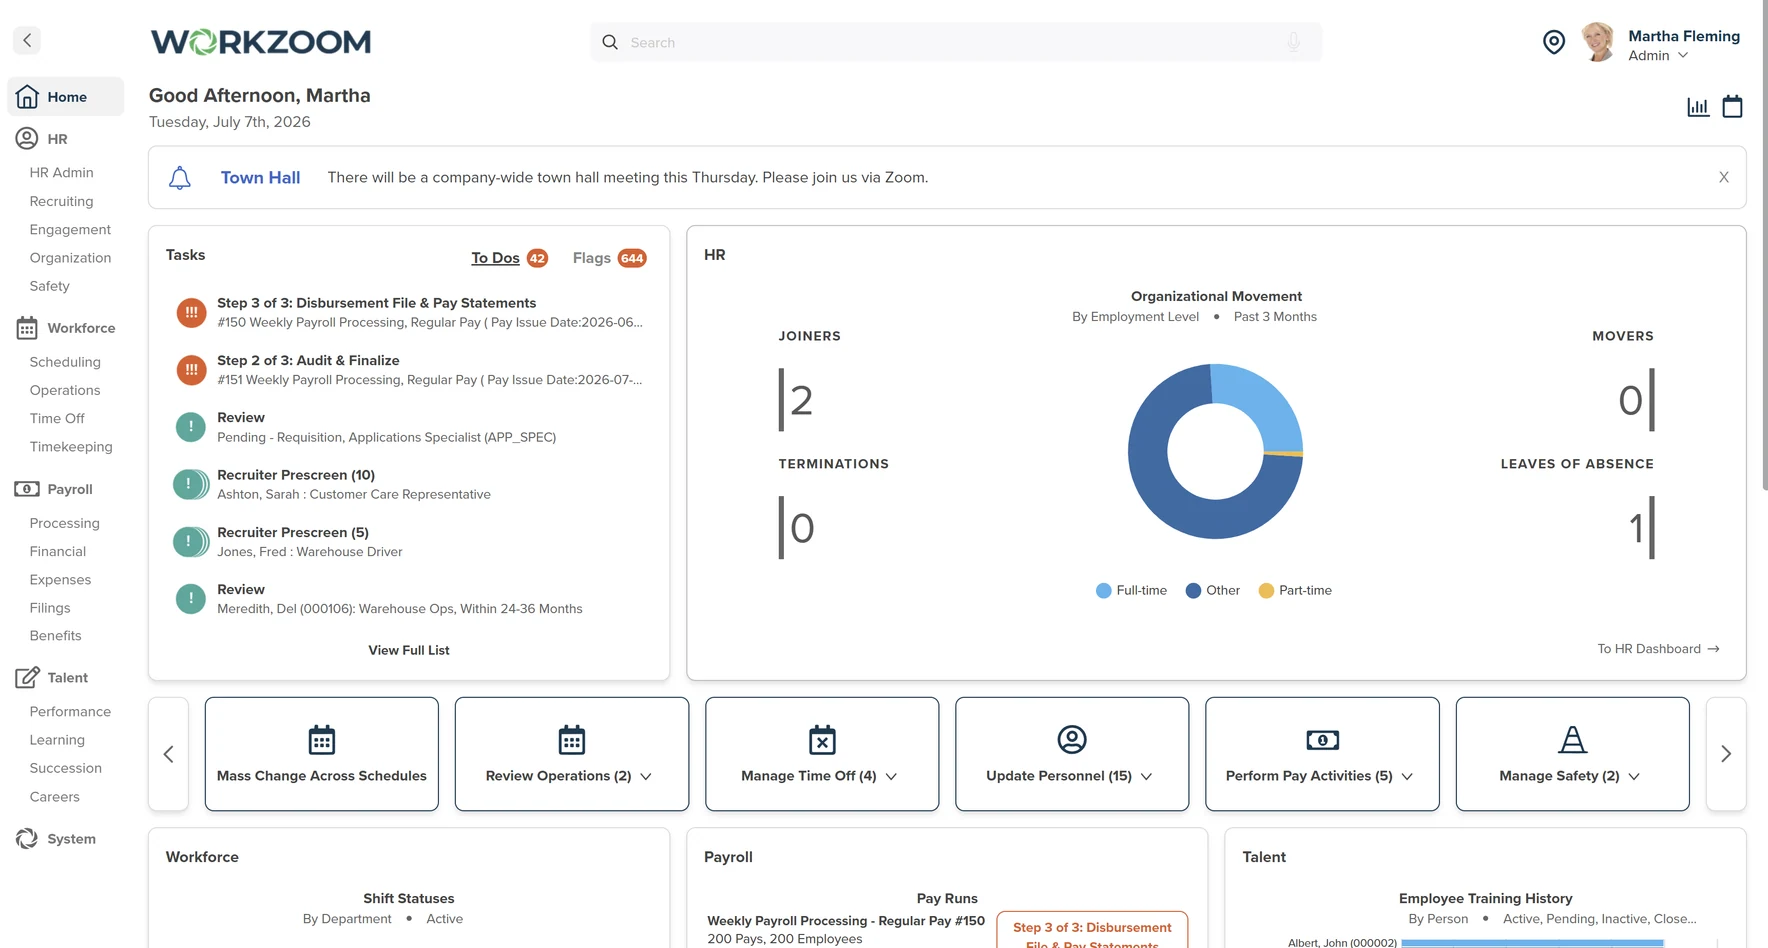
Trinidad and Tobago HR, Workforce, and Talent, available on Workzoom
HR, Workforce, and Talent are available for T&T employers today. Full T&T payroll is on our roadmap. If payroll is part of your evaluation, mention it at your walkthrough. $4/employee/month, implementation included, no long-term contract.
Book a WalkthroughCommon HR and Payroll Mistakes Employers Make in Trinidad and Tobago
The same errors appear repeatedly across foreign-managed operations in Trinidad. They are predictable and preventable.
- Applying a flat NIS percentage instead of using earnings bands. This is the most common payroll error. The NIBTT contribution table maps weekly earnings ranges to fixed contribution amounts. Using a flat 10.8%/5.4% split produces incorrect amounts for most employees. The error is small per pay period but compounds across all employees over time.
- Ignoring the days-worked vacation rule. Where a sector order sets one, granting vacation based purely on anniversary date, without confirming days actually worked, creates inconsistencies. On the other side, denying vacation to employees who have legitimately met the threshold creates grievances.
- Hardcoding public holiday dates. With Divali, Eid-ul-Fitr, and other movable holidays, a static holiday calendar will be wrong every year.
Trinidad and Tobago payroll is a set of interdependent calculations: NIS earnings bands, PAYE bands, and the flat Health Surcharge on top. The days-worked vacation rule, movable public holidays, and the NIS rate increase to 19.2% in 2027 add layers that manual processes cannot reliably track.
The employers who avoid NIBTT back-assessments and Industrial Court disputes are not more careful. They have systems that encode the rules instead of relying on someone remembering them.
- Minimum Wages Order, 2014 (LN 402/2014), clause 5 and Second Schedule item 6, in Minimum Wages Act, Chap. 88:04 claim checked Oct 21, 2026 also Minimum Wages Order, 2014 (LN 402/2014), clause 7, in Minimum Wages Act, Chap. 88:04 (subsidiary legislation)
- Public Holidays and Festivals Act, Chap. 19:05, Schedule (ss 3 and 4) claim checked Oct 21, 2026
- Minimum Wages (Catering Industry) Order, 1991 (LN 158/1991), clause 6(1), in Minimum Wages Act, Chap. 88:04 claim checked Oct 21, 2026
- Minimum Wages (Catering Industry) Order, 1991 (LN 158/1991), clause 7(1), in Minimum Wages Act, Chap. 88:04 claim checked Oct 21, 2026
- Maternity Protection Act, Chap. 45:57, s 9(1) claim checked Oct 21, 2026
- Minimum Wages Order, 2014 (LN 402/2014), clause 7, in Minimum Wages Act, Chap. 88:04 claim checked Oct 21, 2026
- Minimum Wages Order, 2014 (LN 402/2014), clauses 3(2) and 7, in Minimum Wages Act, Chap. 88:04 (subsidiary legislation) claim checked Oct 21, 2026
- Minimum Wages Order, 2014 (LN 402/2014), clause 5 and Second Schedule item 5, in Minimum Wages Act, Chap. 88:04 claim checked Oct 21, 2026 also Minimum Wages Order, 2014 (LN 402/2014), clause 7, in Minimum Wages Act, Chap. 88:04 (subsidiary legislation)
- Minimum Wages (Shop Assistants) Order, 1991 (LN 159/1991), clause 6(1), in Minimum Wages Act, Chap. 88:04 claim checked Oct 21, 2026
- Minimum Wages (Household Assistants) Order, 1991 (LN 160/1991), clause 7(1), in Minimum Wages Act, Chap. 88:04 claim checked Oct 21, 2026
- Minimum Wages (Shop Assistants) Order, 1991 (LN 159/1991), clause 7(1), in Minimum Wages Act, Chap. 88:04 claim checked Oct 21, 2026
- Minimum Wages (Household Assistants) Order, 1991 (LN 160/1991), clause 8(1), in Minimum Wages Act, Chap. 88:04 claim checked Oct 21, 2026
- Maternity Protection Act, Chap. 45:57, s 8(1)(a) claim checked Oct 21, 2026
- Maternity Protection Act, Chap. 45:57, s 9(2) claim checked Oct 21, 2026
- Retrenchment and Severance Benefits Act, Chap. 88:13, s 18(2) and (3) claim checked Oct 21, 2026
- Retrenchment and Severance Benefits Act, Chap. 88:13, s 3(1)(a) claim checked Oct 21, 2026
- Retrenchment and Severance Benefits Act, Chap. 88:13, s 4(1) claim checked Oct 21, 2026
- Retrenchment and Severance Benefits Act, Chap. 88:13, s 6 claim checked Oct 21, 2026
- Industrial Relations Act, Chap. 88:01, s 2(1), definition of "trade dispute" claim checked Oct 21, 2026
- Industrial Relations Act, Chap. 88:01, s 10(4) and (5) claim checked Oct 21, 2026
How useful was this page?
What should we improve?
What readers ask after this post on HR payroll Trinidad and Tobago.
Our clients
The teams that run their people on Workzoom.
Workzoom handles HR, payroll, workforce, and talent on one employee record. Book a Walkthrough.
Related reads
View all in Caribbean

Get started
Built around your org. See it run live.
Explore your suite options, pricing and fit in a 15 to 60 minute working session.
For organizations with 50 or more employees. See our minimums.