 Canada
 United States
 Bahamas
 Jamaica
 Trinidad & Tobago
 Antigua & Barbuda
 Barbados
 Anguilla
T4 Slip Canada: The T4A Mix-Up CRA Won't Let Slide
Somewhere in Canada right now, a payroll administrator is staring at a T4 slip wondering if Box 16 should match Box 14. It should not. And the fact that this trips up experienced payroll people every single year tells you everything about how unnecessarily confusing the CRA has made this process.
A T4 slip in Canada is the official Statement of Remuneration Paid that employers issue and file when the reporting conditions apply under the CRA. It reports employment income, tax deducted, CPP and EI contributions, and taxable benefits for the previous calendar year. T4 slips and the T4 Summary are due by the last day of February following the calendar year the information return applies to. When that due date falls on a Saturday, a Sunday, or a public holiday recognized by the CRA, the return is considered on time if the CRA receives it, or it is postmarked, on or before the next business day.
We process thousands of T4s through Workzoom every year-end, and we have seen the same five mistakes come back like clockwork. This guide covers what is on a T4, when it is due, how to fix errors, and the penalties that hit when things go sideways.
What Is a T4 Slip in Canada and Who Needs One?
The T4, officially called the "Statement of Remuneration Paid," is the CRA's record of what you paid each employee during the calendar year. A T4 is generally required when CPP/QPP, EI, PPIP or income tax was deducted, or remuneration exceeded $500. CRA also specifies additional reporting conditions, including certain taxable benefits and payments. Separate slips may be needed for different provinces of employment or payroll accounts.
That includes part-time staff. Seasonal workers. The summer student who worked six weeks. Apply the deduction and remuneration reporting conditions to each person.
There is a related slip, the T4A, for applicable non-employment payments. Employer retiring allowances generally belong on a T4 using codes 66 and 67, subject to CRA special-case instructions. Do not mix the slip types.
One thing that catches smaller employers off guard: even if an employee earned so little that no deductions were required, you may still need to issue a T4 if you reported the income as pensionable or insurable. When in doubt, file it. The CRA does not penalize you for issuing a T4 that was not strictly necessary. They absolutely will for not issuing one that was.
The T4 Deadline: Last Day of February, and the CRA Means It
T4 slips and the T4 Summary are due by the last day of February following the calendar year the information return applies to. When that due date falls on a Saturday, a Sunday, or a public holiday recognized by the CRA, the return is considered on time if the CRA receives it, or it is postmarked, on or before the next business day. That is the date by which you must:
- File all T4 slips and the T4 Summary with the CRA
- Distribute individual T4 slips to every employee
There is no extension beyond the rollover rule above. The CRA does not care that your payroll system was being migrated, or that your payroll person was on leave, or that you just discovered a taxable benefit you forgot to track all year.
For 2025 remuneration, the deadline was March 2, 2026. For 2026 remuneration, it is March 1, 2027 under the same rollover rule. Do not plan around the grace day. Plan around getting it done early enough that you can catch errors before they are submitted.
The fix is boring on purpose. Track taxable benefits on every pay run, as opposed to reconstructing a year of car allowances, parking, and group life premiums in the last week of February. A T4 should be a printout of work you already did, not a research project.
The employers who panic in February are almost always the ones who left taxable benefits tracking to year-end. Track them on every pay run. February becomes boring. That is the goal.
What Is on a T4 Slip: The Boxes That Matter
A T4 has over 30 boxes. Not all of them will apply to every employee. But the ones that apply need to be right, because the CRA cross-references them against your remittance records and your employees' personal tax returns.
Here are the boxes that cause the most confusion.
Box 14: Employment Income
This is the big number. Total employment income before deductions. It includes salary, wages, bonuses, commissions, taxable allowances, and the taxable value of benefits. Employment income is generally reported in the year paid, even when the work occurred earlier.
The mistake people make: leaving taxable benefits out of Box 14 but including them in Box 40. Box 14 needs the full picture. If an employer-paid group life insurance premium creates a taxable benefit, it goes in Box 14 and gets detailed in the relevant benefit box.
Box 16: Employee's CPP Contributions
This is the employee's CPP contribution through payroll deductions. For Quebec employees, QPP uses boxes 17 and 17A instead. Neither box reports the employer match.
Box 16 will not match Box 14. It should not. CPP is calculated only on pensionable earnings between the basic exemption ($3,500) and the year's first CPP ceiling (currently $74,600). If Box 16 hits the year's employee maximum, that just means the employee earned above the ceiling. Normal.
Box 16A: Employee's CPP2 Contributions
New since 2024. This reports the employee's second additional CPP contributions on earnings between the first and second ceilings. If your employee earned above the first ceiling for the year, this box will have a value, calculated at 4% on the band between the first ceiling and the second ceiling (currently $85,000). If they earned below the first ceiling, it will be blank.
CPP2 is still tripping up payroll software that has not been updated. If your Box 16A does not look right, check whether your system is treating CPP2 as a separate ceiling calculation or incorrectly rolling it into the base CPP rate.
Box 18: Employee's EI Premiums
Total EI premiums deducted from the employee during the year. Remember that Quebec employees pay a reduced EI rate because QPIP covers parental benefits separately. If you have employees in multiple provinces, spot-check the Quebec slips to make sure they reflect the lower rate.
Box 22: Income Tax Deducted
Total income tax deducted for the T4, excluding Quebec provincial income tax, which is reported on the RL-1. This box matters enormously to your employees because it determines whether they owe money or get a refund when they file their personal return.
If this number is wrong, your employee finds out in April when the CRA sends them a notice of reassessment. That conversation is never pleasant.
Box 10: Province of Employment
The province or territory of employment under CRA’s rules, including its reporting-to-an-establishment and full-time remote-work attachment tests. Keep this separate from the employee’s home address.
With remote work, determine province of employment using CRA's employer-establishment test. A full-time remote employee may be reasonably attached to an establishment, while an employee with no attachment may use the paying establishment. A home-address change alone does not decide Box 10.
Electronic Filing: It Is Not Optional Anymore
As of January 2024, an employer that files more than 5 information returns (slips), such as T4 slips, for a calendar year is required to file them electronically, using Internet file transfer or Web Forms. Apply the current threshold by return type; employers below it may still choose electronic filing. Check the CRA's T4 filing guidance for any change since.
You have three options for electronic filing:
- CRA Web Forms: Manual data entry through the CRA website. Free but painful for anything more than a handful of slips. You are typing every box for every employee.
- Internet file transfer (XML): Your payroll software generates an XML file and you upload it through CRA's secure portal. This is how most mid-size employers do it.
- Payroll software with CRA-ready file generation: The software generates a CRA-ready file from your live payroll data. You review, approve, and upload it. Fastest and least error-prone.
The XML route is where errors concentrate. If your software exports the file but you have not reconciled your payroll data first, you are just submitting errors faster.
Penalties for Late or Incorrect T4 Filing
The CRA's penalty structure for late T4 filing is scaled, not flat, and it is merciless either way.
For filing after the deadline: The CRA's penalty for filing T4 information returns late is calculated per day based on the number of slips filed late, ranging from $10 a day for 1 to 50 late slips up to $75 a day for 10,001 or more late slips, with a minimum penalty of $100 and a maximum penalty ranging from $1,000 up to $7,500 depending on the number of slips. The penalty is calculated per information return (the summary), not per slip.
For failing to file electronically when required, the CRA charges a separate wrong-format penalty scaled to how many slips you filed on paper, calculated per type of return. $125 to $2,500 wrong-format filing penalty by slip-count band, per return type, not a flat rate.
For incorrect information on T4 slips, if the error results in a shortfall of remittances, the CRA will assess the difference plus interest dating back to when the correct amount should have been remitted. This guide does not restate a further per-instance penalty figure for repeated errors, since that figure has not cleared this page's own verification standard; confirm it directly with the CRA before relying on it.
And here is the part nobody mentions. If the CRA finds that you under-remitted because of T4 errors (say, you forgot to include a taxable benefit in pensionable earnings), the penalty is not just on the T4 itself. They reassess the CPP and EI contributions you should have remitted throughout the year. With interest. Going back to the first pay period where the error occurred.
Determine the income-tax, CPP/QPP, and EI/QPIP treatment of each benefit separately. Do not assume every taxable benefit is pensionable and insurable.
How to Amend a T4 Slip
You filed. You found an error. Now what.
The good news: you can amend T4 slips after filing. The CRA accepts amended slips at any time. The bad news: amending does not erase the penalty for the original error if it resulted in a remittance shortfall.
Amending Online
If you filed electronically, you can submit amended T4s through the same channel. The CRA's system will match the amended slip to the original using the employee's SIN and the tax year.
Amending by Paper
If you need to amend a slip filed through Web Forms or XML, you can submit a paper amendment by marking the T4 as "Amended" and mailing it to your tax centre. But realistically, electronic amendment is faster and creates a clearer audit trail.
What Triggers an Amendment
The most common reasons we see employers amend T4s:
- Discovered a taxable benefit that was not tracked during the year (parking, group insurance, company vehicle)
- Employee's province of employment was coded incorrectly
- A payment-year reporting error or an amount omitted from the T4
- CPP or EI over-deduction that was not caught before filing
If the amendment is in the employee's favour (you over-withheld), they will get it back when they file their personal return. If the amendment means they owe more, you need to issue the corrected T4 so their return is accurate. Either way, amend promptly. Do not wait and hope nobody notices.
The Five T4 Mistakes We See Every Year
After 25 years of Canadian payroll, these are the errors that never seem to die. Every February. Like clockwork.
1. Taxable benefits vanish into thin air
Employer-paid group life insurance premiums. Personal use of a company vehicle. Employer-paid parking. Gift cards. Their treatment depends on CRA rules and the facts; some gifts, awards or parking arrangements can be non-taxable. Employer-paid group life premiums are a taxable benefit, calculated by policy type. $500-a-year non-cash gift exemption with conditions and exclusions; gift cards are taxable near-cash unless they meet strict non-cash conditions See the CRA's taxable benefits guidance for the full list of what counts. Every year, employers forget to track at least one of them.
The fix is not a year-end audit. The fix is including taxable benefits on every pay run so they are already calculated by the time T4 season arrives. If you are scrambling to calculate the standby charge on a company vehicle in February, you are already behind.
2. CPP pensionable earnings do not match
Box 26 (CPP pensionable earnings) and Box 14 (employment income) are related but not identical. Certain income types are included in Box 14 but exempt from CPP. When these boxes do not reconcile logically, the CRA's automated matching flags the return for review.
3. Province of employment defaults to head office
Your company is in Ontario and a remote developer lives in Nova Scotia. Do not assign Box 10 from the home address alone: apply CRA's employer-establishment and attachment analysis, then document the result.
4. Forgetting to issue T4s for terminated employees
Someone left in March. You paid them severance. You issued their final paycheque. Then year-end rolls around and they are not in the "active" employee list anymore, so the system skips them. Or worse, you assume someone else handled it.
Apply the same CRA reporting conditions to current, terminated, retired and leave-of-absence employees. Include everyone for whom a slip is required.
5. Filing the T4 Summary with wrong totals
The T4 Summary (T4-SUM) is the roll-up of all individual T4 slips. The totals on the Summary must match the sum of all individual slips, and they must reconcile with your total remittances for the year. A mismatch between your Summary and your remittance account is the fastest way to trigger a CRA balance-due notice.
The T4 is not a standalone document. It is the final reconciliation of everything your payroll system did all year. If your payroll data is clean, T4s are a formality. If it is not, T4 season is where every shortcut catches up with you.
Quebec Employers: RL-1 Slips Are a Separate Obligation
If you have employees in Quebec, you are not just filing T4s. You also file RL-1 slips with Revenu Quebec. Same deadline. Different form, different boxes, different rules.
The RL-1 reports Quebec-specific deductions: QPP instead of CPP, QPIP (Quebec Parental Insurance Plan), and Quebec provincial tax. The boxes do not map 1:1 to the T4, which means you cannot just copy T4 data into an RL-1 template. The calculations are different in ways that matter.
If your payroll system handles Quebec natively, the RL-1 generates alongside the T4 from the same payroll data. If it does not, you are looking at a manual reconciliation process that is tedious, error-prone, and due the same day everything else is due.
What Year-End Looks Like When the Data Is Clean
County of Renfrew, an Ontario municipal employer with roughly 900 employees, onboarded 32 new staff in three months with zero paper. By the time February arrived, their T4 filings came from the same system that ran every pay run. Workzoom calculates and prepares the T4 output. The employer reviews and submits to CRA. No export-to-spreadsheet step. No reconciliation sprint.
Ktunaxa Nation, with over 200 employees across multiple entities in B.C., files T4s for each governance entity from the same payroll system. Each slip is prepared from live payroll data. The CPP2 calculations are native. The province of employment is tracked per employee, not defaulted to head office. The February deadline is a formality, not a project.
That is the difference. Not smarter teams. Systems that track taxable benefits on every pay run, handle province of employment updates when they happen, and prepare filings from the data that already exists. The Ontario ESA and provincial standards that govern what counts as taxable income are documented in the Ontario Employment Standards Act guide, and T4 accuracy depends on tracking those obligations correctly throughout the year. Payroll software that integrates with those requirements is what makes February boring on purpose.
T4 slips generated from the payroll data you already have
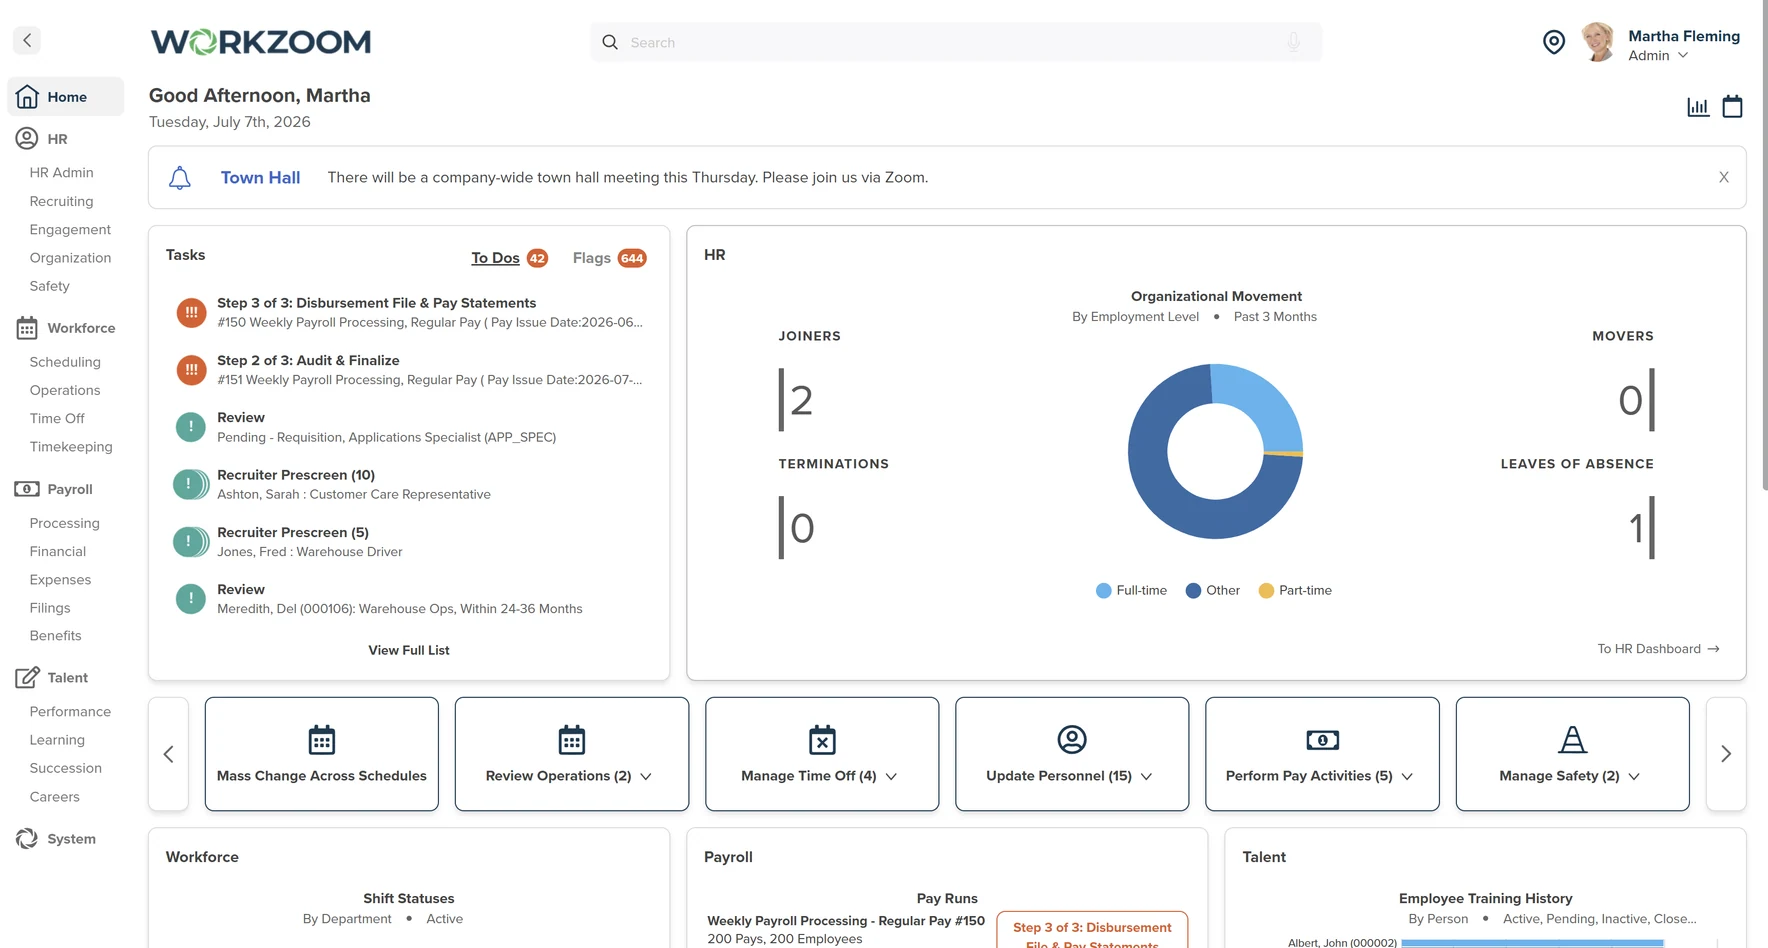
Workzoom produces T4s, T4As, and RL-1s directly from the same system that runs your payroll. No exports, no reconciliation sprint. Starting at $4/employee/month with no setup fees, no contracts.
See How Year-End WorksIf your current process involves exporting to spreadsheets and hoping your T4 Summary matches your remittances, the system is the problem. And the system is fixable.
- When to file information returns claim checked Sep 4, 2026
- File information returns electronically (tax slips and summaries) - Get ready to file in effect since Jan 1, 2024 claim checked Sep 4, 2026
- Employers' Guide - Filing the T4 Slip and Summary (RC4120) claim checked Sep 4, 2026
- File information returns electronically (tax slips and summaries) - Get ready to file claim checked Sep 4, 2026
- Premiums and contributions to insurance plans claim checked Sep 4, 2026
- Gifts, awards, and long-service awards in effect since Jan 1, 2022 claim checked Sep 4, 2026
See Workzoom in 30 minutes.
Real product, real questions, no slides. Starts at $4 per employee per month, CAD or USD, with $0 setup fees.
What readers ask after this post on T4 slip Canada.
Our clients
The teams that run their people on Workzoom.
Workzoom handles HR, payroll, workforce, and talent on one employee record. Book a 30-minute walkthrough.